
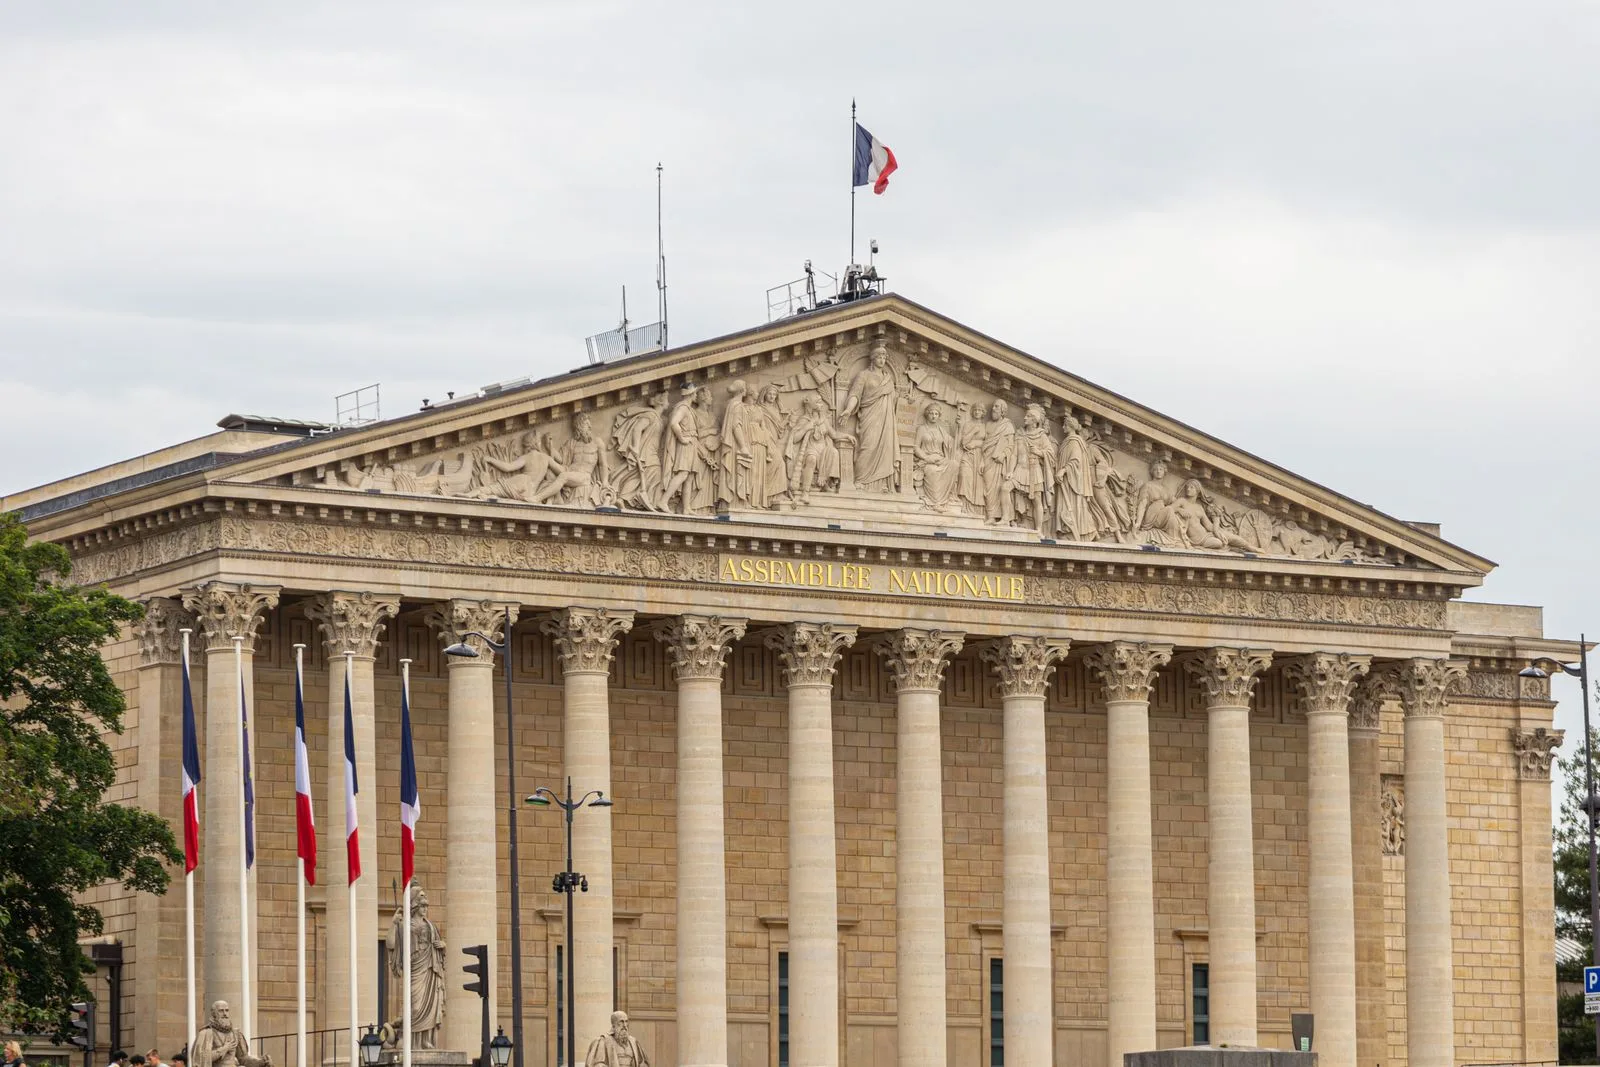
For fifteen years, the eurozone had a simple pecking order. Germany was the anchor. France was the co-pilot. And Greece was the cautionary tale that finance ministers told each other late at night.
On Thursday the pecking order broke. Investors demanded 177.7 basis points more to lend to France for ten years than to Germany, according to Reuters. That is the widest gap since November 2011, at the height of the euro crisis. The equivalent figure for Greece was 106. For Italy, 123. For Spain, 70.
Read that again. The markets now treat the country that co-wrote the euro's rules as a bigger risk than the country those rules were last used to discipline. France's ten-year yield touched 5.14% on Thursday, its highest since July 2002.
Tonight, after Wall Street closes, Moody's gives its verdict. It has rated France Aa3 since December 2024 and switched the outlook to negative a year ago, citing, as Dow Jones reported, "the increased risk that the fragmentation of the country's political landscape will continue to impair the functioning of France's legislative institutions." Fitch and S&P already sit a notch lower. Most economists expect Moody's to follow.
A downgrade will make headlines. The more interesting story is how France got here, and who is quietly being lined up to catch it.
The street and the market want opposite things
France is being squeezed from two sides at once, and they are pulling in opposite directions.
On the street, the demands are for more: more teachers, smaller classes, higher pay, cheaper fuel. What began in September as school protests in the Paris suburbs grew, as EUobserver recounts, into a revolt against living costs, a public-sector pay freeze and a proposed austerity budget, and on 17 October into riots.
In the bond market, the demand is for less. Prime Minister Sébastien Lecornu says he is targeting €54 billion in spending cuts. France ended last year with a deficit of 5.1% of GDP, CNBC notes, against an EU ceiling of 3%. The IMF, cited by ARD, expects public debt to reach 118.5% of GDP this year. France has not balanced a budget since 1974.
And in between sits a parliament that cannot agree on anything. This year's budget was forced through in February without a vote. Finance Minister Roland Lescure told RTL on Wednesday that the government is ready to do it again: "We have the tools to get it passed." If things go wrong, he said, "we'll activate the guardrails."
The guardrail, in this case, is Article 49.3 of the constitution, which lets the government adopt a bill without the National Assembly voting on it. A democracy whose emergency brake is skipping the vote is not a democracy with a spending problem. It is a democracy with a consent problem, and the bond market has noticed.
"Because it is France"
None of this came out of nowhere, and Brussels knows it.
In May 2016, Jean-Claude Juncker, then Commission president, was asked why the EU executive kept giving Paris extra time on its deficit. His answer, reported by Reuters, was disarmingly honest: "because it is France." France had been given two more years in 2015 despite missing its targets.
The Dutch chairman of the Eurogroup, Jeroen Dijsselbloem, saw where this led. "If we turn a blind eye everywhere, we make a blind monetary union," he said, according to Euractiv.
Ten years on, here we are. Greece got the troika, pension cuts and inspectors in Athens. France got patience. The rules were strict for small countries and polite for big ones. And it turns out the markets never signed that gentlemen's agreement.
The rescue has a clause in it
The comforting answer in Paris is that the European Central Bank will step in if things get ugly. It has a tool for exactly that: the Transmission Protection Instrument, created in 2022, which allows unlimited purchases of a country's bonds.
But read the ECB's own terms. The tool is for a "deterioration in financing conditions not warranted by country-specific fundamentals." France's problem is its fundamentals. And the first eligibility criterion is "compliance with the EU fiscal framework: not being subject to an excessive deficit procedure (EDP), or not being assessed as having failed to take effective action" under the EU treaty.
France is under an excessive deficit procedure. The ECB says its criteria are only an input and keeps the final call for itself. But whether its firepower can ever be pointed at Paris hinges, in large part, on a judgement from Brussels: whether France is taking "effective action". That is the same Brussels that once explained its leniency with four words.
For now, nobody expects Frankfurt to move. "We believe the bar for the ECB to intervene is very high," Nomura's Andrzej Szczepaniak told Reuters. The ECB meets on 29 October. Citi's Giada Giani made the political point more delicately: "re-emerging euroscepticism is a constraint here."
Translated: German, Dutch and Austrian voters will want to know why the discipline that flattened Athens is about to be read generously for Paris. They will be right to ask.
The fix has to be French
There is a centre-right answer to all this, and it is not cheering for a downgrade. France matters too much to Europe, and its people are too proud, for anyone to enjoy watching it be priced like the periphery.
The answer is that France's crisis is French, and so must be the cure. A budget passed by elected deputies who own it, not by decree. Spending cuts argued for in public, not rushed through by constitutional shortcut. A government that tells protesters honestly that the money has run out, instead of quietly hoping that Frankfurt or Brussels will find more.
Voters will get their say in April's presidential election. Marine Le Pen, the frontrunner, has promised to bring the deficit below 3% within 18 months, a claim critics doubt. Doubt is fair. But at least it is a promise a French government would have to keep in front of French voters, rather than one Brussels would have to pretend was kept.
Whatever Moody's says tonight, the market has already given its rating. For a decade, Europe's rules bent for France because it was France. Now France pays more than Greece, for the same reason.
Update, 24 October 2026: Late on Friday, Moody's left France's rating at Aa3 with a negative outlook, sparing Paris the downgrade markets had priced in. The agency said the rating assumes a deficit-reducing 2027 budget is adopted and that financing costs and social tensions ease somewhat, Reuters reports. In other words: a reprieve, on conditions France has yet to meet.